

I. The "Puff Count" Race Continues to Surge-But It's Increasingly Becoming a Mere "Specs War"
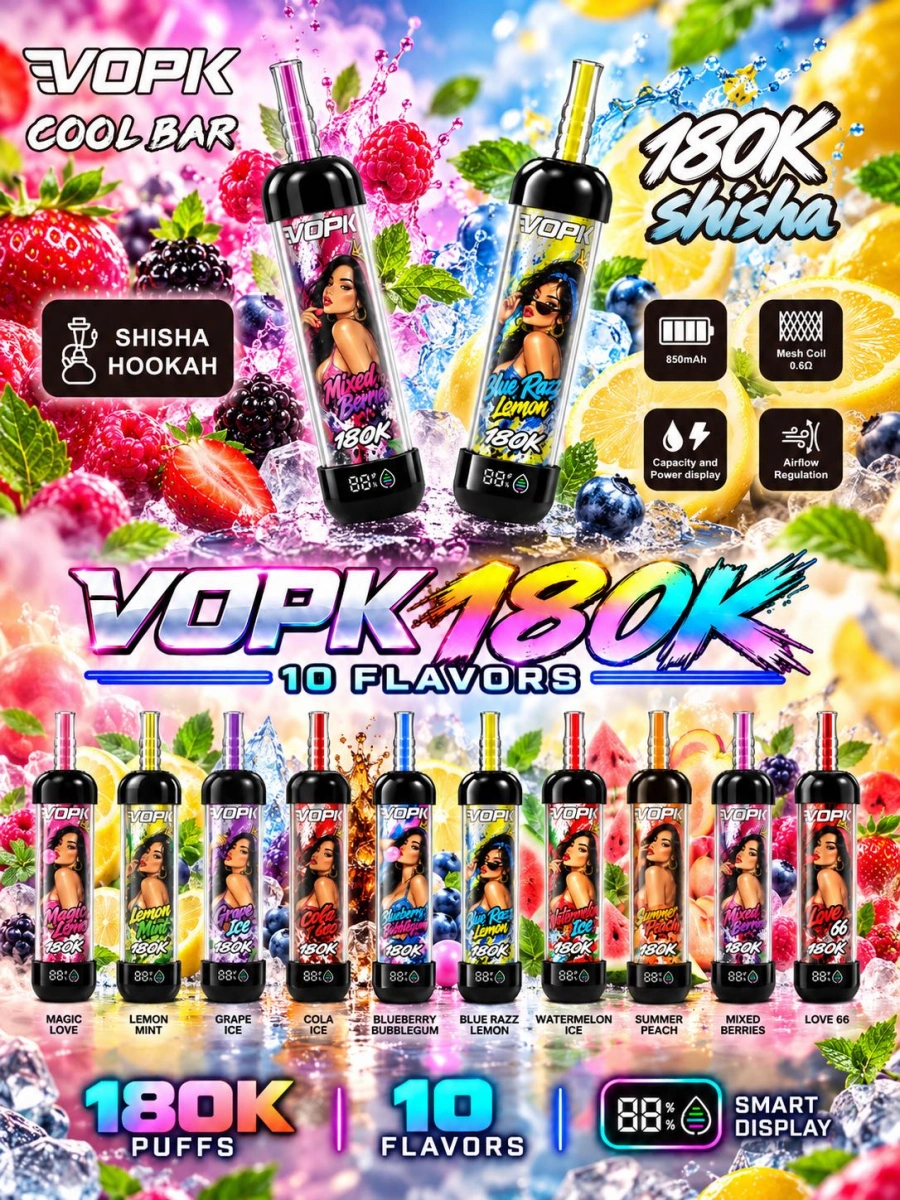
Looking at the most prominent trend heading into the first half of 2026, puff counts continue to climb-from 20,000 or 30,000 to 50,000, 60,000, and even 80,000 puffs. In the Canadian market, high-puff-count products keep pushing the upper limits of longevity, while in the U.S., brands like Foger are leveraging modular designs to shift "high-puff" devices from single-use disposables toward reusable systems. This confirms that a market for high-puff-count products persists; for heavy users, in particular, the reduced frequency of device replacement and the longer lifespan per purchase offer clear, tangible value. Yet, a problem arises: when products boasting 50,000 or 80,000 puffs become commonplace, can the puff count itself still serve as a genuine competitive moat for a brand? The answer is likely no. Every mature manufacturing industry follows a similar trajectory: initially, technical specifications represent innovation; later, they become marketing selling points; and finally, once everyone can replicate them, they simply become the industry standard. Consequently, the next phase of competition may no longer be about who reaches 100,000 puffs first, but rather about who can solve a more pressing, practical challenge: not how to make the puff count even higher, but how to ensure that every single puff truly delivers value.
II. Disposable e-cigarettes are gradually evolving into "semi-durable goods." If a high puff count stands out as the most prominent product trend for 2026, another, perhaps more significant, shift is the blurring line between disposable and pod-based (refillable/replaceable) e-cigarettes. An increasing number of products now occupy the space between these two categories. Modular designs, for instance, allow users to retain the battery component while replacing the e-liquid reservoir or the atomization unit. This effectively resolves a core contradiction inherent in traditional disposables: users desire the convenience of a disposable device, yet they may not want to purchase an entirely new unit every single time. The growing interest in modular products stems from their ability to strike a new balance between these two product formats-maintaining simplicity for the user while extending the product's lifecycle for the brand. With a modular approach, the commercial relationship shifts: purchasing a device → replacing consumables → exploring new flavors → upgrading modules → remaining within the brand's ecosystem. This represents a pivotal change; historically, the e-cigarette industry has relied heavily on the constant acquisition of new users. Moving forward, however, the true value lies not merely in selling more devices, but in how effectively a brand can retain a user within its ecosystem over the long term.
III. Screens are growing larger, and the e-cigarette industry is entering an era of "interactive competition." By 2026, screens have become increasingly common in e-cigarette products. The Geek Bar SPARK, for example, features a dynamic screen and integrates both pre-filled and refillable pod systems on a single platform; according to official specifications, it includes an 800mAh battery with fast-charging capabilities and offers users a choice between pre-filled and refillable pods. Similarly, the Elf Bar ELFX MEGA incorporates a screen, a high-capacity 2800mAh battery, 32W power output, Turbo/Eco modes, and dual-mesh coil technology into an open-system device. This signals a clear transformation: e-cigarettes are evolving from simple "atomization devices" into "interactive consumer electronics." While the screen itself is not the core competitive advantage, it signifies a fundamental shift in product design philosophy-a trajectory that closely mirrors the development path of other consumer electronics, such as smartphones and smartwatches. As hardware gradually matures, experience design has emerged as a new competitive battleground.
IV. Ultimately, it is the market-not technical specifications-that determines a product's fate. A look at the e-cigarette landscape reveals a striking trend: the best-selling products in different countries are becoming increasingly distinct. When Geek Bar launched the "SPARK" in March 2026, it did not simply replicate its U.S.-market "PULSE" model for Europe; instead, it introduced a system that emphasizes reusability and supports both pre-filled and refillable configurations. This reflects an emerging reality: no single e-cigarette product-based on a uniform product logic-can dominate the global market. The U.S., Europe, and Canada each require tailored product structures, shaped by unique regulatory environments, consumer habits, retail channels, and pricing models. Consequently, the most competitive brands of the future may not be those that create a single "global hit," but rather those that operate as global brands with localized product offerings. This places a new set of demands on Chinese e-cigarette companies: researching local markets, understanding regulatory boundaries, defining region-specific products, and managing local distribution channels.
V. Regulation is redefining who gets to stay in the game. While high puff counts may drive product-level competition, regulation determines who remains eligible to compete at all. This is already evident in the development trajectories of brands like Vuse and VEEV. In recent years, the primary advantage of "native" e-cigarette brands has been speed-rapid product development, agile supply chains, frequent iterations, and quick flavor updates. A product could go from R&D to production and market entry in just a few months-a pace traditional tobacco giants struggled to match. However, as market regulations raise the bar, the rules of the game are shifting. Companies no longer face the simple question, "Can we create a product?" but rather, "Can we create a product that can legally enter this market?" These are, in fact, two entirely different business capabilities. This is precisely why traditional tobacco giants are regaining an edge. While they may not boast the fastest product iteration cycles, they possess mature regulatory compliance frameworks, established global distribution networks, long-term capital, strong brand equity, and the organizational capacity to navigate shifting regulatory landscapes. A distinct trend is likely to emerge in the e-cigarette industry: while product innovation is accelerating, market access is becoming increasingly sluggish. Only those capable of addressing both challenges simultaneously will be able to build genuine, long-term competitiveness.
VI. The 2026 E-Cigarette Market: A Tale of Two Worlds. Looking at the overseas market landscape in the first half of the year, two clear, diverging paths have surfaced. The first path focuses on "extreme value for money." Key markets include parts of the U.S., Canada, and other regions where there is still a strong demand for high-capacity products. Core attributes include high puff counts, large e-liquid capacity, low cost-per-use, long battery life, and modular design. The underlying logic is straightforward: users want a single purchase to last as long as possible. The second path centers on "compliance and reusability." Key markets include the U.K., Germany, France, Italy, and other regions with stricter regulatory environments. Core attributes include replaceable pods, reusable devices, TPD (Tobacco Products Directive) compliance, platform-based product architecture, and a focus on long-term consumer relationships. This approach addresses the fundamental question: "How can we ensure continued user engagement within a regulated framework?" Conclusion: The trend toward high puff counts will persist, but the industry itself has fundamentally shifted. In the first half of 2026, the overseas e-cigarette market presents a dichotomy: on one hand, products are being pushed to the limits of performance; on the other, regulations are actively reshaping product design. While disposable products continue to evolve, brands are simultaneously returning to pod-based systems, reusable devices, and long-term user engagement. This suggests that the e-cigarette industry may not follow a single, unified trajectory. Instead, it is evolving into a landscape where multiple markets and distinct product philosophies coexist. For e-cigarette companies, this marks an era that demands a fresh perspective. The critical question for the future is no longer just about innovation, but rather: "Which specific market are we targeting, and what kind of product are we building for it?" The race for higher puff counts will continue, but the e-cigarette industry has begun to diverge onto separate paths.